Key Takeaways
- Central Banks Are Buying Record Amounts of Gold: Governments around the world are stockpiling gold to diversify their reserves and protect against economic uncertainty.
- Silver Is Driven by High-Tech Demand: Beyond its value as an investment, silver is essential for expanding industries like solar power, electronics, and AI infrastructure.
- Recent Price Drops Are Normal Market Corrections: While gold and silver prices have pulled back recently, temporary pullbacks are a normal part of long-term market trends.
- Precious Metals Provide Portfolio Protection: Gold and silver don’t rely on the stability of any single government or bank, making them a reliable hedge against inflation and market volatility.
- Major Analysts Predict Strong Future Growth: Top financial institutions forecast significant price increases for both gold and silver over the next few years.
Precious metals have experienced extraordinary volatility during the first half of 2026. After reaching new all-time highs in January, both gold and silver have undergone substantial corrections, prompting many investors to ask the same question:
Has the precious-metals bull market run its course?
Large corrections are not unusual during long-term commodity bull markets, particularly in assets as globally traded and macroeconomically sensitive as precious metals.
Current market conditions resemble a correction within a longer-term trend rather than evidence that the investment thesis has fundamentally changed. Price momentum has weakened, but many of the structural forces supporting precious metals remain largely intact.
This report examines those forces in detail.
Inflation Remains Uncertain
Financial markets often treat inflation as a simple binary: low inflation is good, high inflation is bad. In reality, precious metals care less about today’s headlines and far more about where monetary policy, interest rates, and long-term purchasing power are headed.
Federal Reserve Chair Kevin Warsh has emphasized that monetary policy remains committed to long-run price stability, warning markets not to assume inflation risks have permanently cleared. Central banks remain acutely aware that unexpected energy spikes, supply disruptions, or fiscal pressures can quickly reignite price pressures.
This is exactly why central banks are loading up on gold, which brings us to our next section.
Central Banks Are Stockpiling Gold
One of the defining characteristics of the current gold market is that governments-not individual investors-have become some of its largest buyers. This is exactly why the long term growth case for precious metals remains intact.
According to the World Gold Council, central banks bought a net 244 metric tonnes of gold in Q1 2026 alone—a 17% quarter-over-quarter increase. Over the past four years, official purchases have averaged roughly 1,000 metric tonnes annually, nearly doubling the pace of the previous decade.
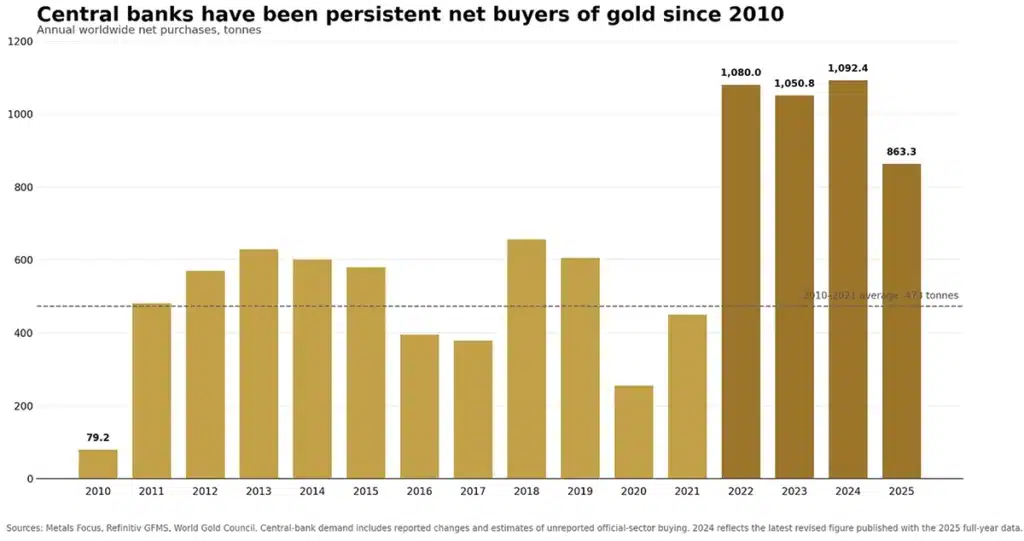
This is not a temporary trend. In the WGC’s 2026 survey, 89% of reserve managers expected global central bank holdings to rise over the next year—the highest consensus ever recorded. Countries like Poland, China, Uzbekistan, and Kazakhstan continue to lead the buy side.
Why Are Central Banks Buying Gold?
Understanding why central banks are accumulating gold helps explain why many analysts believe today’s market differs from previous precious-metals cycles.
The first motivation is reserve diversification. Although the U.S. dollar remains the world’s dominant reserve currency, prudent reserve management has always emphasized diversification across multiple asset classes. Gold provides exposure to an asset whose value is not directly linked to the fiscal or monetary policies of any single government.
Second, gold occupies a unique place among reserve assets because it carries no counterparty risk. A Treasury bond represents a claim on the U.S. government. A bank deposit represents a claim on a financial institution. Foreign-exchange reserves consist largely of claims on other sovereign borrowers. Gold is fundamentally different.
A physical gold bar stored in a central-bank vault is not simultaneously someone else’s liability. It cannot default, declare bankruptcy, or require another institution to remain solvent in order to preserve its value.
That distinction has become increasingly important in recent years. Central banks continue viewing gold as a long-term hedge against monetary uncertainty.
Silver’s Industrial Metal Advantage
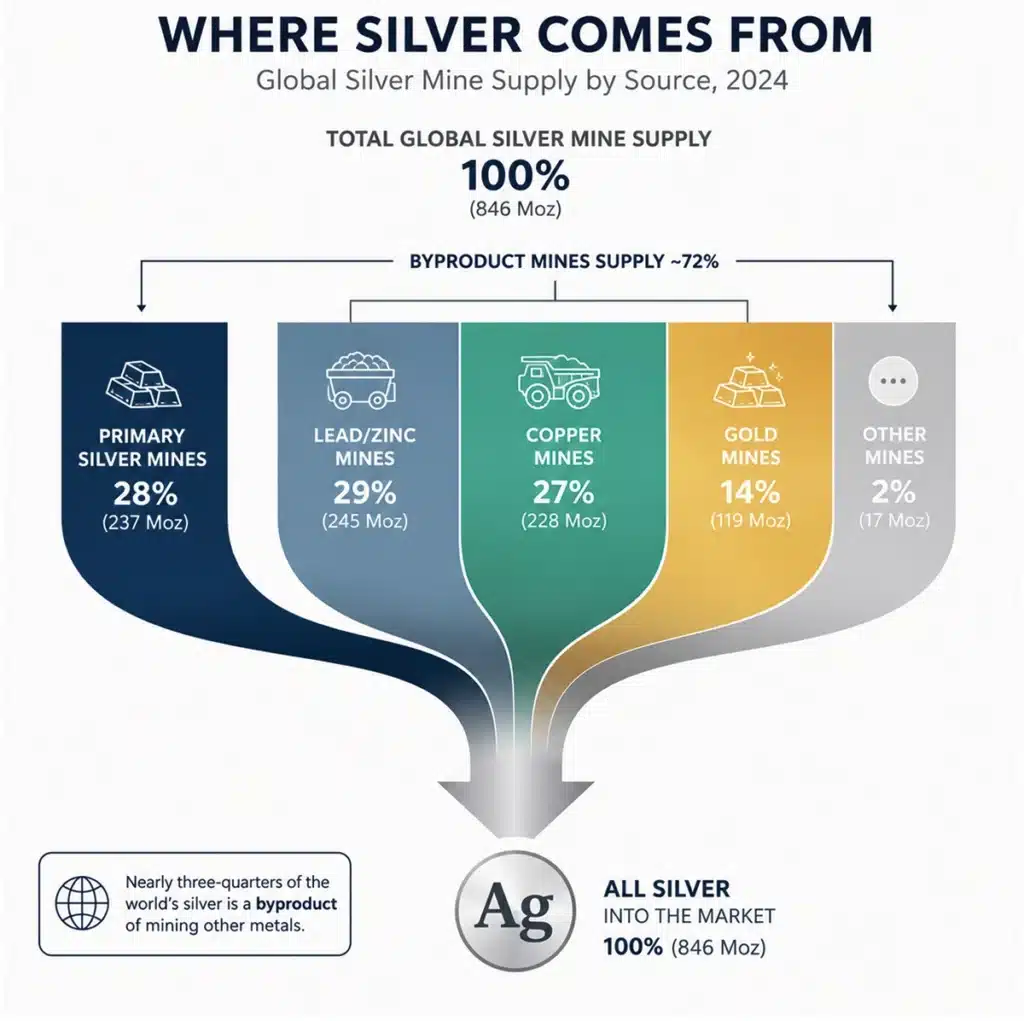
Gold’s demand is driven primarily by investment, jewelry, and official-sector purchases. Silver, by contrast, occupies a far more complex position in the global economy.
Although silver has served as money for much of recorded history, today it is also one of modern industry’s most versatile raw materials. Thanks to its unmatched electrical conductivity, thermal conductivity, and reflectivity, silver plays a critical role in a wide variety of advanced technologies.
Solar photovoltaic panels remain one of the largest and fastest-growing sources of demand. Silver is also used extensively in semiconductors, consumer electronics, telecommunications equipment, medical devices, automotive electronics, high-performance batteries, and countless industrial applications requiring reliable electrical performance.
The rapid expansion of artificial intelligence may further increase silver demand.
AI itself does not consume silver directly, but the enormous infrastructure supporting AI, including hyperscale data centers, power, distribution equipment, networking hardware, advanced cooling systems, and semiconductor manufacturing-depends heavily upon electrical components in which silver remains difficult to replace.
Geopolitics Continues to Influence Precious Metals
Geopolitical flare-ups frequently trigger sharp short-term swings in gold and silver.
Wars, financial crises, sovereign debt concerns, banking instability, and major geopolitical shocks frequently lead investors to seek assets whose value is less dependent upon corporate earnings, credit markets, or the financial condition of individual governments.
While these events can cloud the short-term picture and induce brief price spikes or volatility, investors shouldn’t lose sight of the broader horizon. Geopolitical uncertainty simply reinforces the foundational thesis for precious metals: when global trust and stability are tested, capital naturally moves toward unencumbered physical assets.
Short-term geopolitical noise may move the daily chart, but the long-term structural bull market thesis remains firmly on track.
What Are Price Analysts Forecasting?
No one can predict commodity prices with certainty. Nevertheless, professional forecasts provide a useful snapshot of how major financial institutions currently interpret the balance of risks and opportunities facing precious-metals markets.
While individual projections differ, the broad consensus remains constructive, particularly over the intermediate term.
J.P. Morgan currently projects gold averaging approximately $6,000 per ounce during the fourth quarter of 2026, rising toward $6,300 per ounce by the end of 2027. The firm’s outlook reflects expectations that official-sector demand will remain strong, real interest rates will gradually moderate, and geopolitical uncertainty will continue supporting investor interest in safe-haven assets.
Forecasts for silver are similarly optimistic. The London Bullion Market Association’s annual survey of twenty-six market analysts produced a 2026 consensus forecast of approximately $79.57 per ounce.
J.P. Morgan’s base-case estimate stands near $81, while Goldman Sachs has suggested a range of roughly $85 to $100 per ounce, assuming industrial demand continues expanding alongside ongoing investment demand.
A Half Century of Precious Metal Spikes
The current precious metals environment did not emerge in isolation. Rather, it represents the latest chapter in a series of major economic and monetary transitions that have shaped global markets over the past five decades.
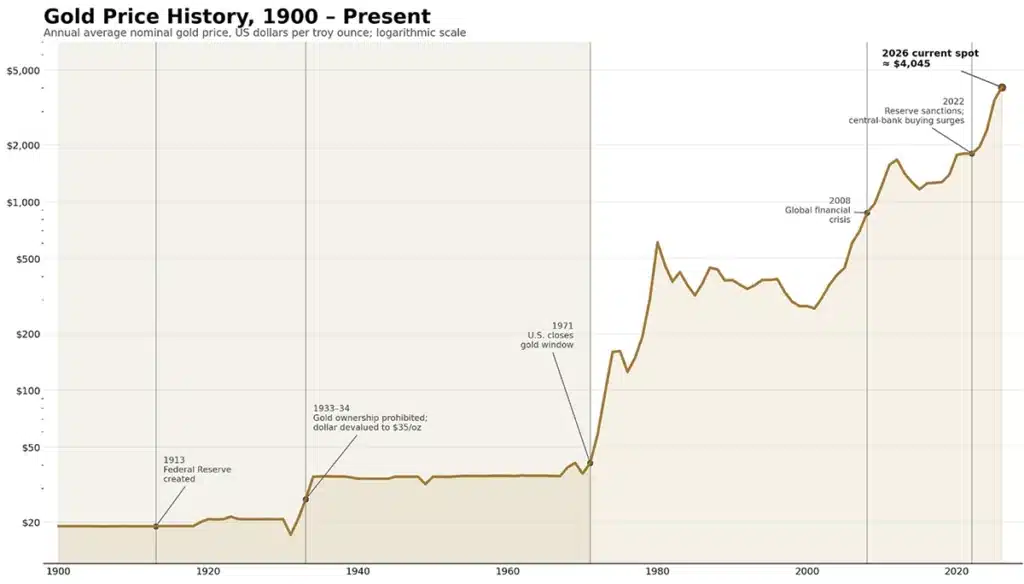
Each of these periods shared different characteristics.
- The 1970s centered on inflation.
- The post-2008 era reflected financial instability and exceptionally accommodative monetary policy.
- The pandemic emphasized inflation, supply-chain disruption, and fiscal expansion.
- The years since 2022 have increasingly highlighted reserve diversification and geopolitical risk.
Gold & Silver as Part of a Diversified Investment Strategy
Perhaps the most important question facing investors is not whether gold or silver will outperform over the next six or twelve months. Rather, it is whether precious metals deserve a place within a well-diversified portfolio over the long run.
History suggests that they often do-but not because they consistently produce the highest returns. Unlike stocks, precious metals do not represent ownership in productive businesses. Unlike bonds, they generate no coupon payments or contractual income streams. They produce no earnings, pay no dividends, and distribute no cash flow.
Their value derives instead from their scarcity, durability, liquidity, and widespread acceptance as stores of value.
Gold and silver can diversify portfolios because they often respond differently than traditional financial assets to changes in inflation, monetary policy, geopolitical events, and financial-market stress.
Looking Ahead
Gold has remained a recognized store of value for thousands of years. Silver has simultaneously retained monetary significance while becoming increasingly indispensable to modern industry.
Their roles have evolved, but neither has disappeared.
As we navigate the second half of 2026 and look toward 2027, the structural pillars supporting precious metals remain robust:
- Central Bank Accumulation
- Industrial Scarcity
- Portfolio Protection
Price corrections in a long-term commodity cycle are normal, healthy, and often create strategic entry points. While short-term volatility is guaranteed, the long-term case for including gold and silver in a resilient, forward-looking portfolio remains as compelling as ever.
 About the author: Peter C. Earle, Ph.D, is the Director of Economics and Economic Freedom and is Head of Research who joined AIER in 2018. He holds a Ph.D in Economics from l’Universite d’Angers, an MA in Applied Economics from American University, an MBA (Finance), and a BS in Engineering from the United States Military Academy at West Point.
Prior to joining AIER, Dr. Earle spent over 20 years as a trader and analyst at a number of securities firms and hedge funds in the New York metropolitan area as well as engaging in extensive consulting within the cryptocurrency and gaming sectors. His research focuses on financial markets, monetary policy, macroeconomic forecasting, and problems in economic measurement. He has been quoted by the Wall Street Journal, the Financial Times, Barron’s, Bloomberg, Reuters, CNBC, Grant’s Interest Rate Observer, NPR, and in numerous other media outlets and publications.
Disclaimer: All opinions expressed by the author are the author’s opinions and do not reflect the opinions of Goldco. The author’s opinions are based on the author’s personal experience, education and information the author considers reliable. Goldco does not warrant that the information contained herein is complete or accurate, and it should not be relied upon as such.